Context
The regulatory plan existed. The product audit did not.
Credit Karma needed to show its products were ready for the UK’s new Consumer Duty rules. The Board had approved a wider programme and Compliance had completed a gap analysis, but nothing assessed the end-to-end member experience across products and teams.
The requirement
Documented evidence of readiness, including avoidance of foreseeable harm, before the July 2023 deadline.
The reality
Journeys had been built piecemeal. No single team held a complete view of a service or the risks running through it.
I designed the product audit and turned its findings into owned action.
Audit scope
Six weeks, focused where the risk was greatest
A full audit wasn’t realistic, so I chose three areas with distinct member and business risks. That gave the audit real breadth without reducing it to a superficial review of every screen.
Member support
Account recovery, thin credit files and disputes drove contacts and complaints.
Car finance
An external provider created an unclear boundary during a consequential journey.
Credit cards
The largest revenue stream, with lessons for other marketplaces.
Approach
I audited the service, not just the screens
An interface review would find usability problems, but not the risks created between teams, support processes, technical systems and partners.
Workshops
Disagreement became evidence
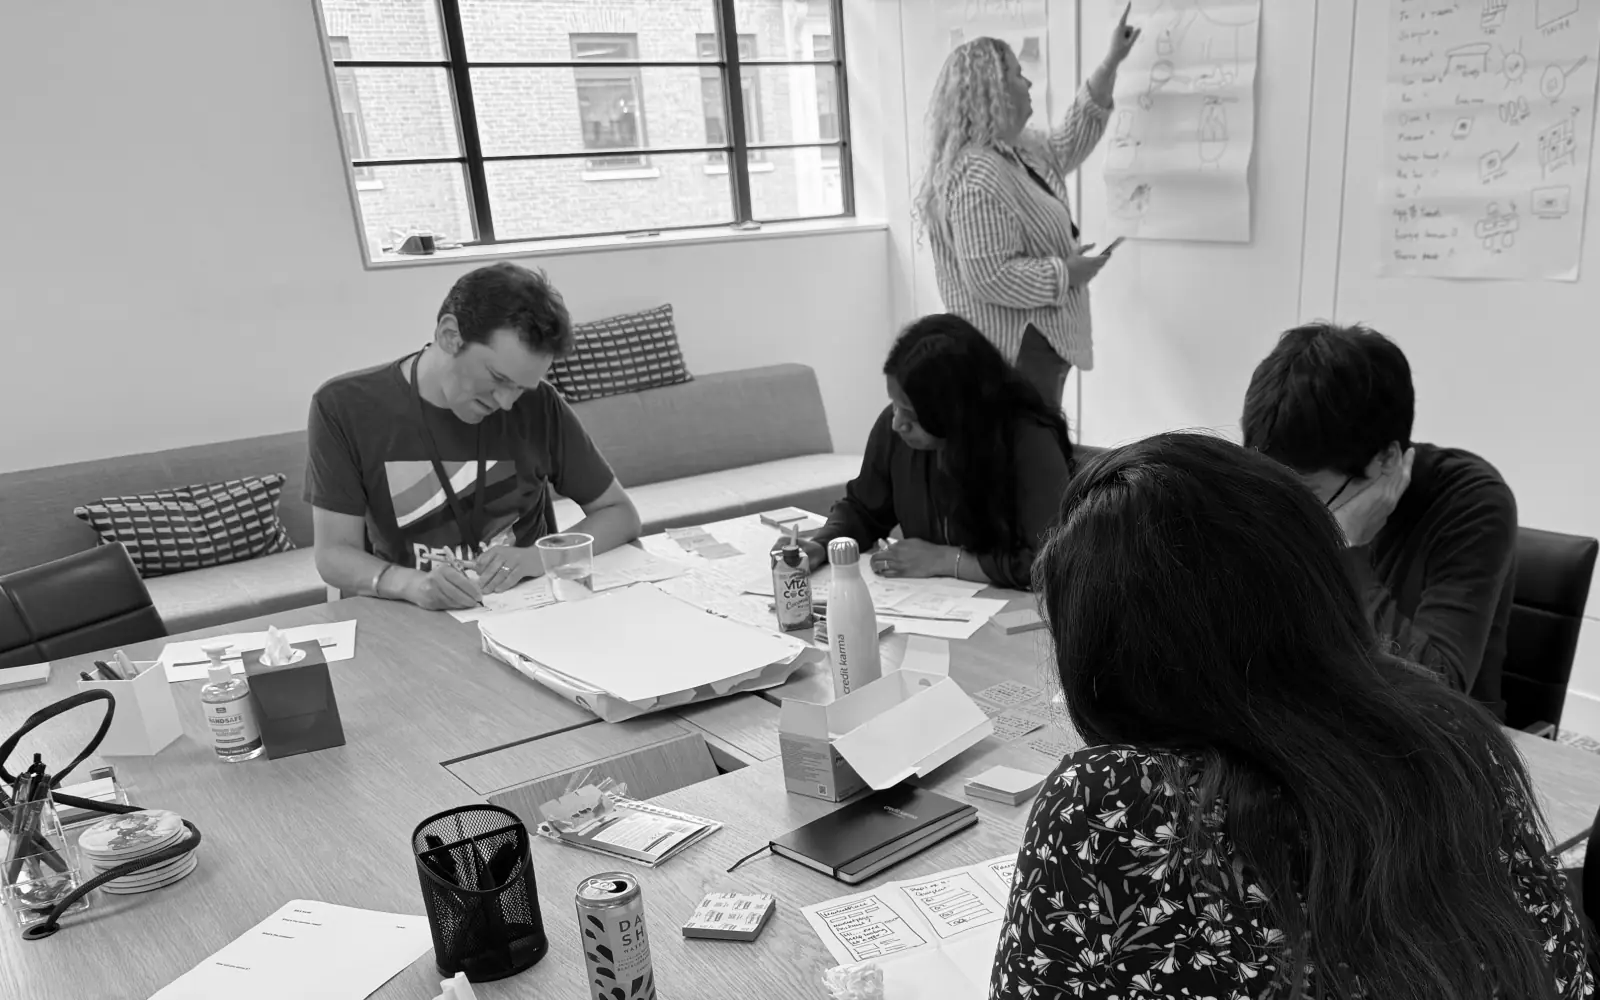
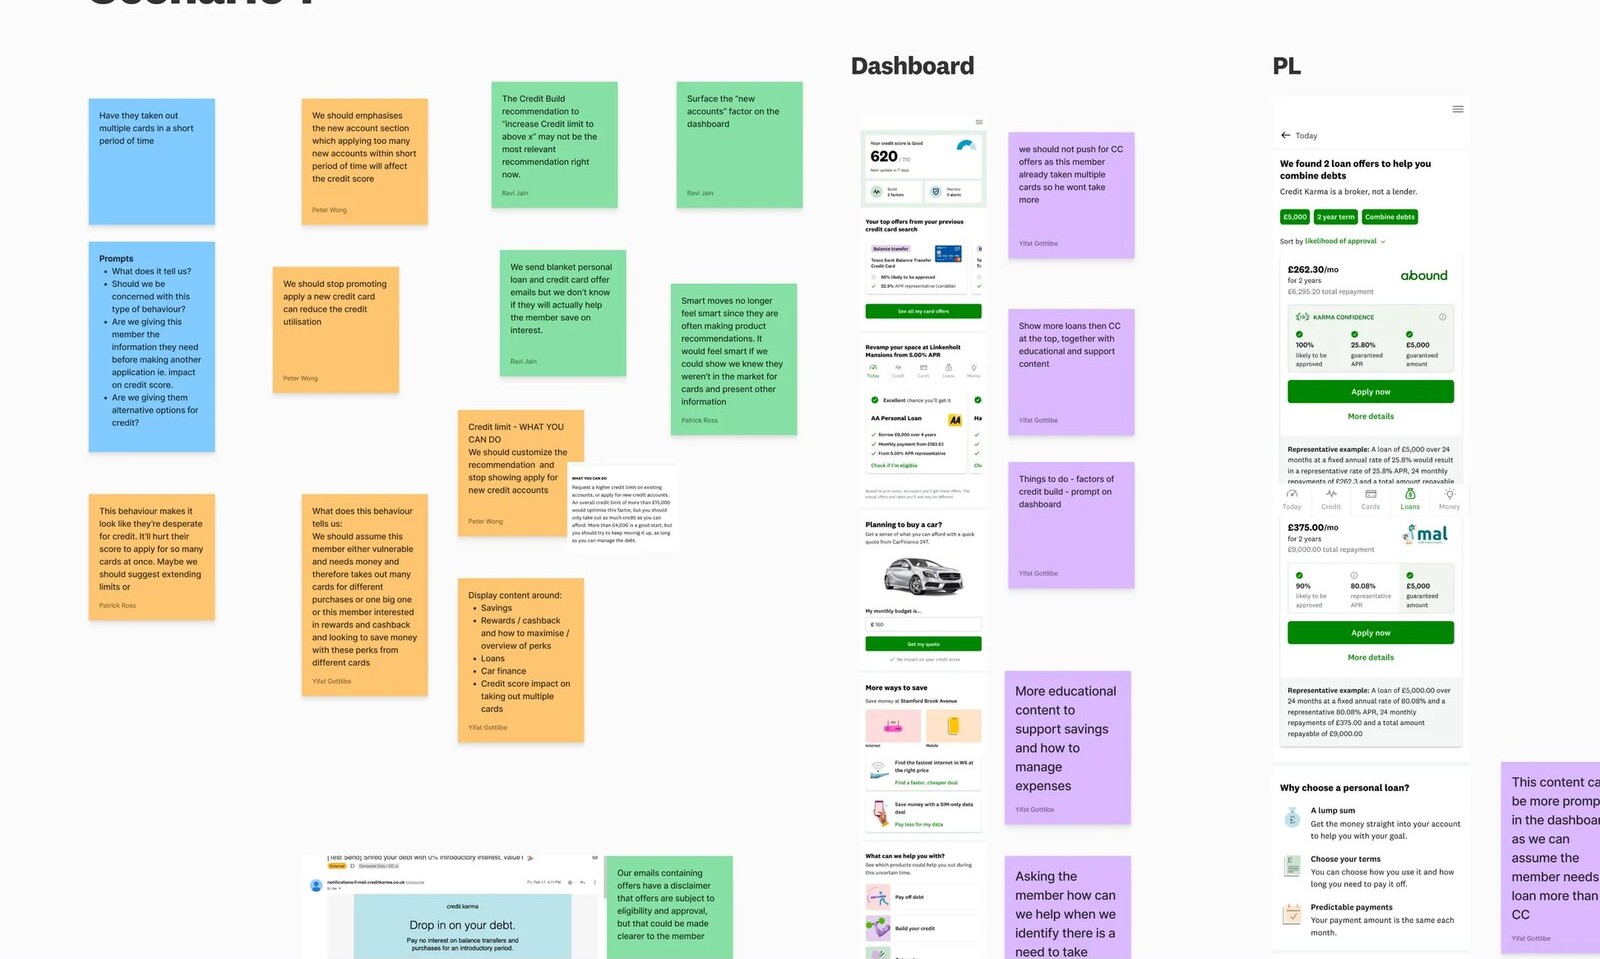
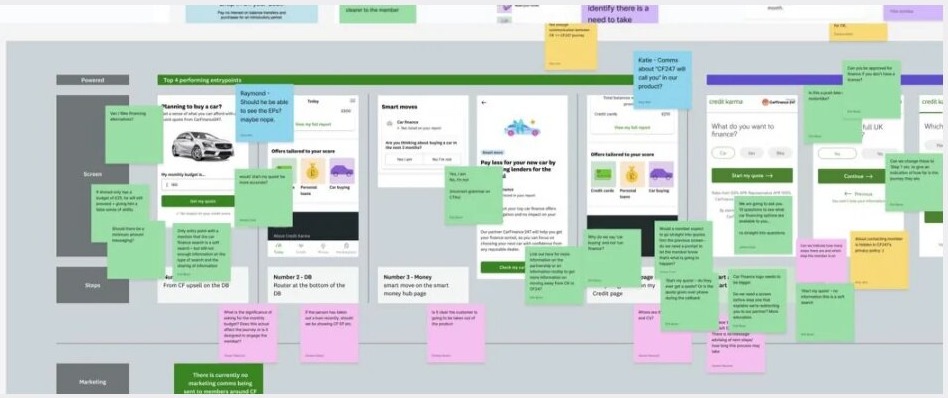
I ran three workshops with around 50 attendances across eight functions. Groups mapped the same journeys independently. Where their maps diverged, the disagreement exposed product, process and ownership risks no single team could see.
Teams then repeated the journeys with vulnerability cards covering dyslexia, temporary impairment, English as an additional language and financial vulnerability. We assessed key content against a reading age of 11 or below.
“I’ve worked here for three years, and this is the first time I’ve looked at the product from a member’s point of view.”
Findings
From small problems to a prioritised backlog
Small problems were creating larger barriers
Individually minor issues combined into journeys that were hard to recover from, and unclear about where Credit Karma’s responsibility ended.
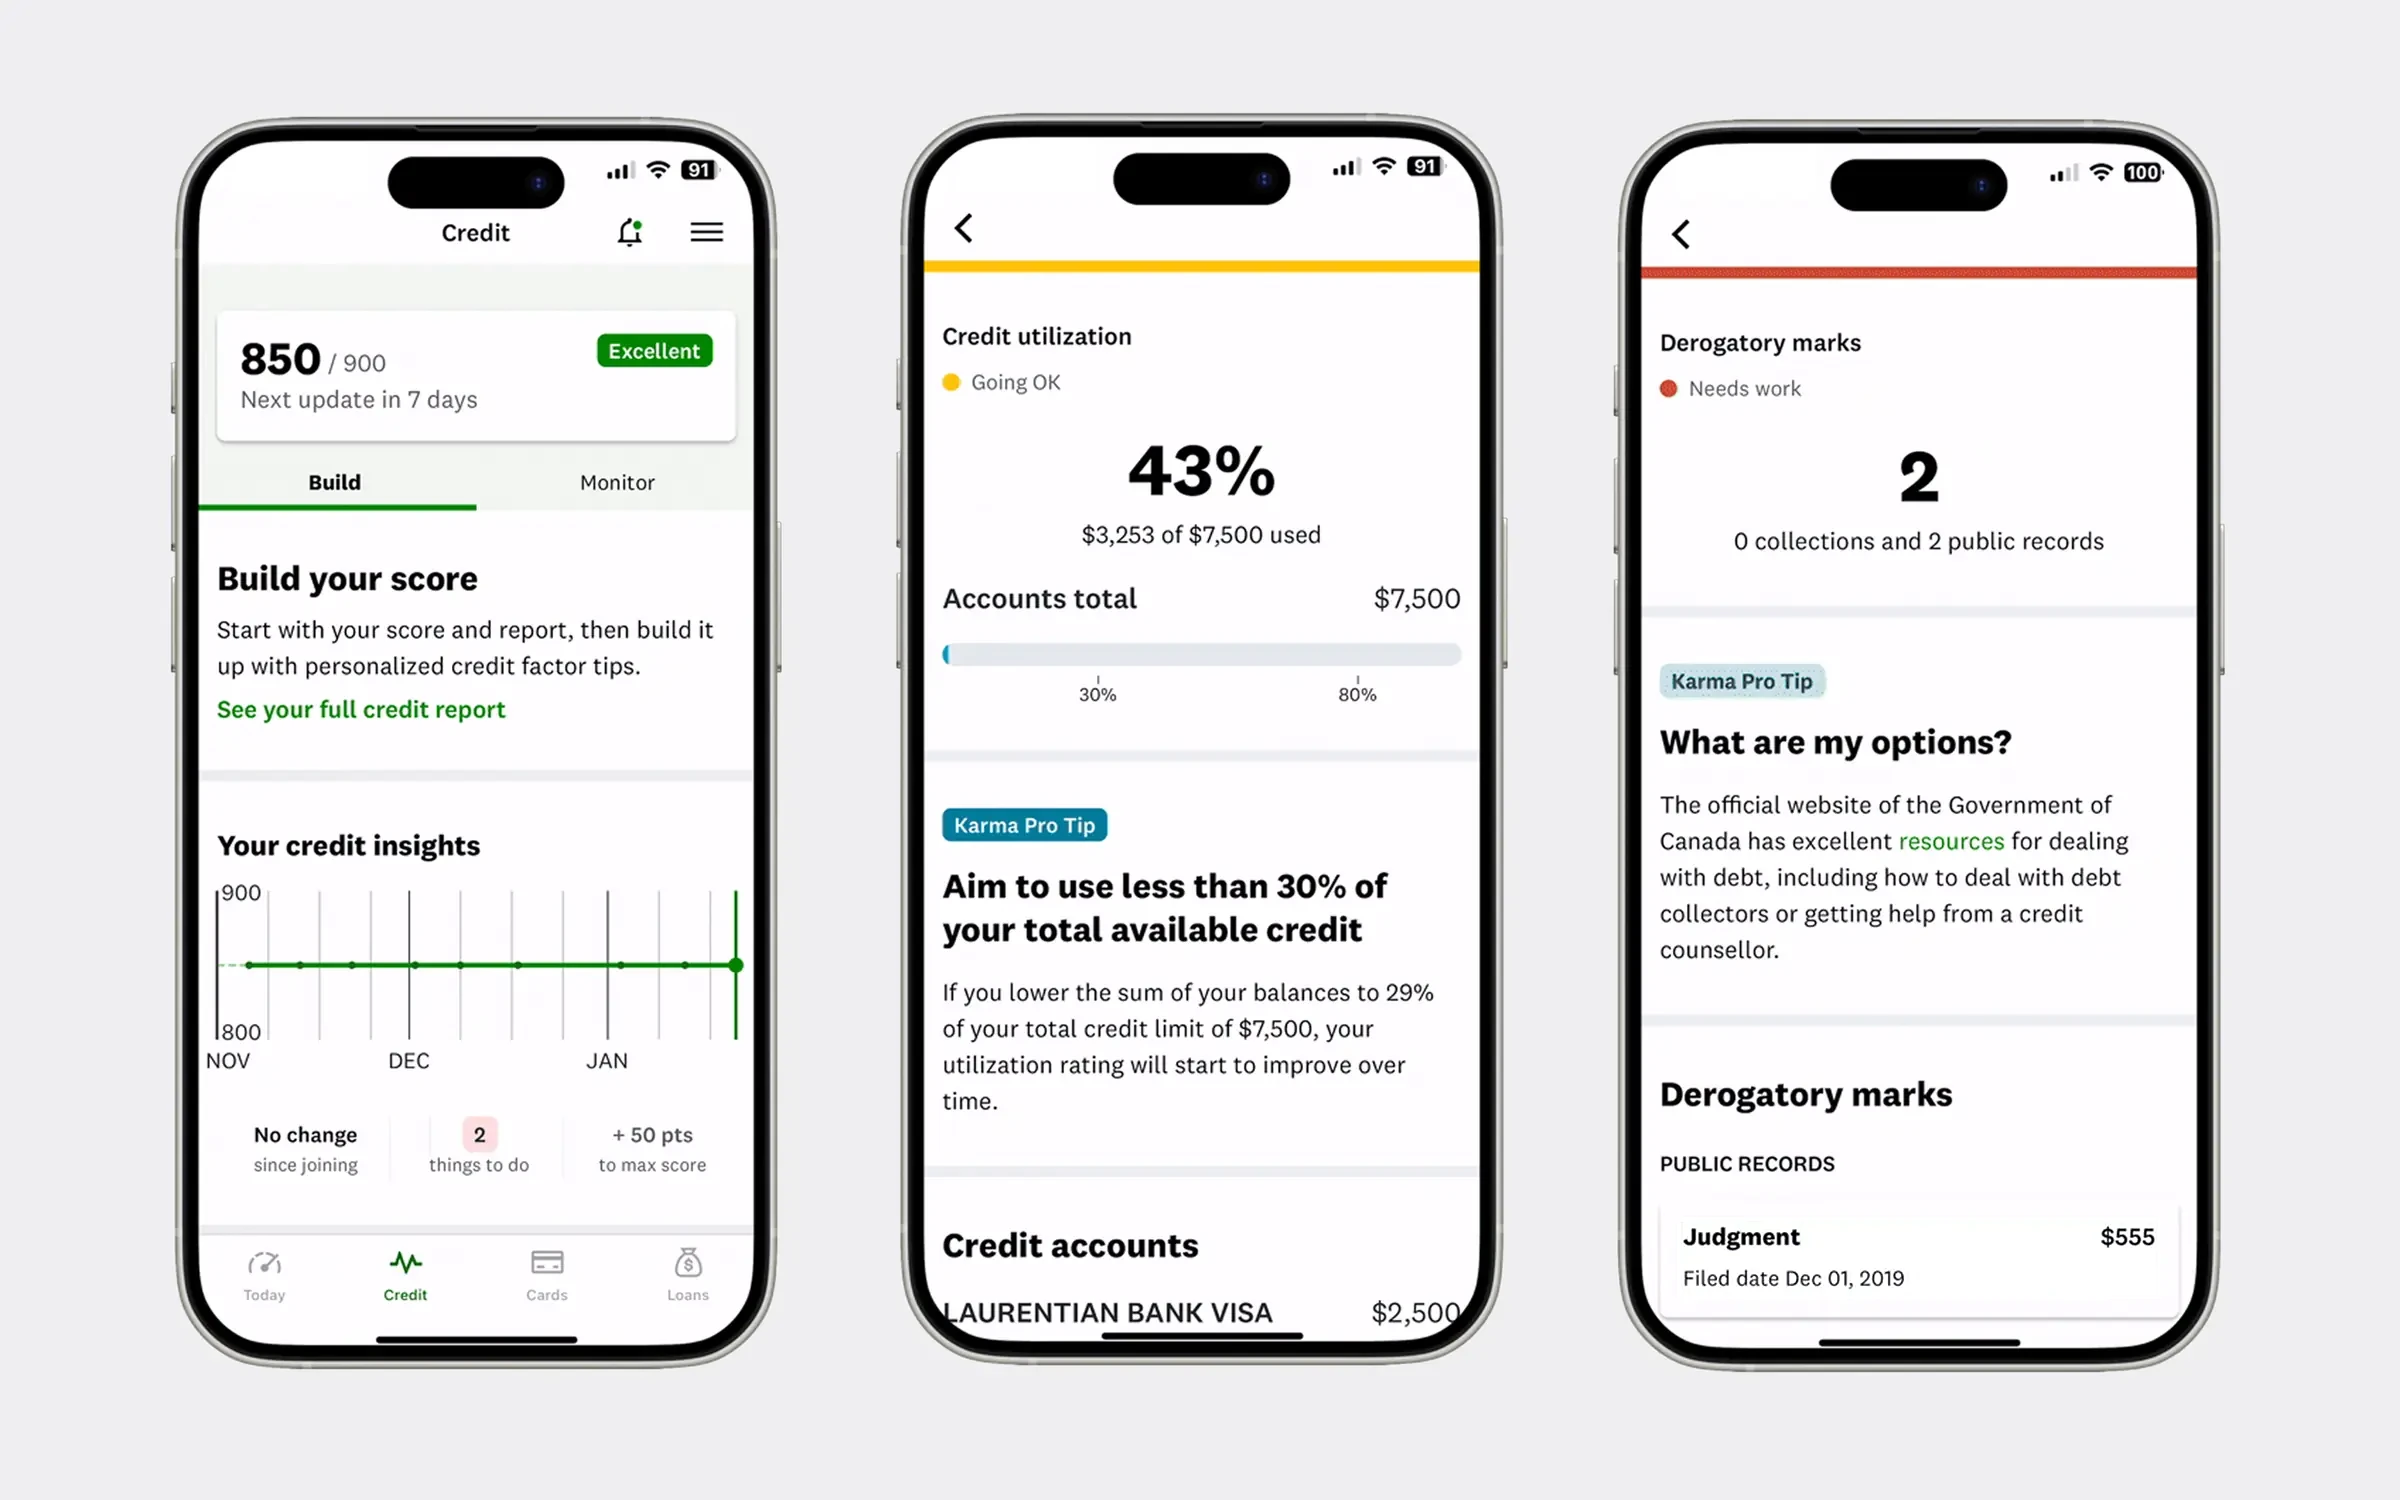
- Account recovery. Password-reset help led to the generic Help Centre.
- Contacting support. Members completed a form, then learned it hadn’t been sent.
- Partner journeys. Members moved to another company’s application without a clear transition.
The members at greatest risk were missing from our test data
QA accounts showed every available card, and employee accounts skewed financially secure. Teams couldn’t reproduce thin files, high debt, defaults or repeated declines, the very circumstances the regulation cares about.
I recommended representative profiles so design, engineering and compliance could test realistic risk states.
What our accounts could show
What they could not
A hidden partner hand-off, made explicit without an extra click
Choosing ‘buy a car’ moved members into a CarFinance247 application. Similar branding hid the hand-off at exactly the point browsing became applying.
Business Development worried an extra step would hurt conversion; Legal and Compliance needed the provider and credit implications to be clear. Both were reasonable, which made it a design problem rather than a policy one.
The workshops were not the output
I tied each finding to a potential harm, then rated it with Design, Product, Engineering, Legal and Compliance together. Running it as a joint estimate separated immediate regulatory risks from longer-term improvements.
This gave the Board product evidence for its readiness assessment, documented in April 2023.
- Evidence
- Potential harm
- Risk
- Effort
- Owner
Every finding ended with a named team and a next action, not a report.
Impact
Support demand fell, and member outcomes shaped product work
fewer account-recovery tickets. Account recovery moved from the number-one support issue in 2023 to number four in 2024.
fewer support contacts. At the organisation’s internal estimate of £100 per contact, this represented around £4 million in equivalent support costs.
fewer queries passed to TransUnion. Fewer member queries were forwarded from Member Support to the credit reporting agency.
Member outcomes became part of product scoping
Product briefs added ‘member outcomes’ and ‘foreseeable harm’, while Compliance champions brought that perspective into teams.
The approach reached beyond the UK
US partners adopted similar workshops for compliance and customer-satisfaction work.
Figures reported across the available comparison periods reflect the wider Consumer Duty programme and the combined work of several teams. The support-cost equivalent is an estimate, rather than a confirmed cash saving.
Reflection
What I learned
Connect the evidence to the decision
Workshops produce observations. Making each one carry a potential harm, a risk rating, an effort estimate and a named owner meant a regulatory obligation reached teams as a backlog they had helped build, rather than a report they had to interpret.
Thanks to
Fadi Dagher Head of Design, Yasser Masood Head of Compliance and everyone across Product, Engineering, Support, Business Development, Legal, Compliance, Risk and Security who took part in the three workshops.